
Foreclosure activity in Alabama has accelerated sharply in 2026, and homeowners who fall behind on payments have less runway than they might assume. Understanding where the numbers stand — and how Alabama’s foreclosure process actually works — is the first step toward keeping your prevention options open.
Alabama Foreclosures at a Glance (2026)
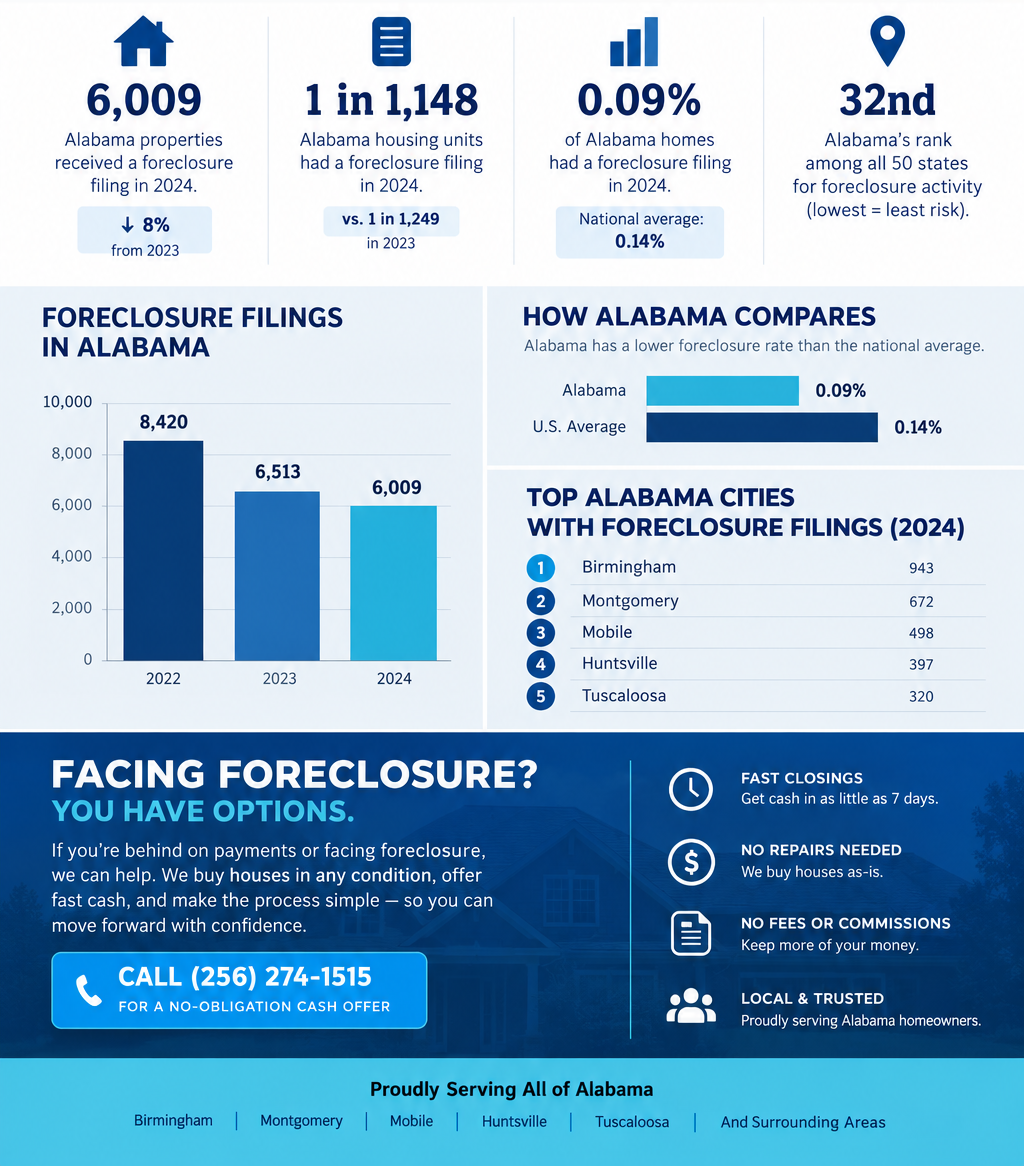
- Alabama foreclosure starts rose 26.6 percent year-over-year, climbing from 2,466 in the first half of 2025 to 3,359 in the first half of 2026 — one of the largest increases of any U.S. state.
- Completed foreclosures (bank repossessions) in Alabama more than doubled in the first quarter of 2026, jumping from 153 to 355 properties.
- The national mortgage delinquency rate stood at 4.37 percent of all outstanding loans at the end of the second quarter of 2026, with 0.67 percent of loans in the foreclosure process.
- Nationally, one in every 3,603 housing units had a foreclosure filing in July 2026.
- Alabama posted one of the highest vacancy rates among investor-owned homes in the country, at 5.9 percent in the third quarter of 2026.
- Alabama homeowners get a full one-year statutory right of redemption after a foreclosure sale — longer than many neighboring states.
Why Alabama’s Numbers Are Climbing
The rise isn’t isolated to one corner of the state. ATTOM’s data shows Alabama’s foreclosure filing rate ranked 14th worst nationally in early 2026, with total filings up nearly 39 percent year-over-year. At the same time, national mortgage performance has softened: the Mortgage Bankers Association’s survey found delinquencies rose 40 basis points from a year earlier at the start of 2026, driven in part by rising distress among FHA and VA borrowers as pandemic-era relief programs expired. When national lending stress ticks up, states like Alabama — with a fast, lender-friendly foreclosure process — tend to see completed foreclosures follow quickly.
Alabama Moves Fast — That’s the Part Homeowners Underestimate
Alabama is a non-judicial foreclosure state, meaning a lender doesn’t need a court order to foreclose — it can proceed under the power-of-sale clause already written into most mortgages. State law requires publishing notice of the sale in a local newspaper once a week for three consecutive weeks, and lenders must mail homeowners a redemption notice at least 30 days before the sale by certified mail. Beyond that, there’s no mandatory court review, no judge, and no extended docket delay — the timeline from missed payments to auction day can be a matter of weeks once the process formally starts.
The one piece of good news: Alabama’s one-year right of redemption lets certain parties — including the original homeowner, their spouse, and heirs — reclaim the property after the sale by repaying the purchase price plus interest and lawful charges. But redemption requires cash most distressed homeowners don’t have on hand, which is why acting before the sale date is almost always the better path.
Options Before the Auction Date
If you’re behind on payments in Alabama, you generally have more leverage the earlier you act:
- Loan modification or repayment plan — negotiating new terms directly with your servicer.
- HUD-approved housing counseling — a free resource for understanding your servicer’s requirements and deadlines.
- Short sale — selling for less than what’s owed, with lender approval.
- Selling for cash before the sale date — closing on your own timeline, paying off the mortgage, and avoiding a foreclosure entry on your credit history altogether.
This is where Best Homes & Property Solutions can help. We buy Alabama houses directly, as-is, with no repairs, no agent commissions, and no financing contingencies to fall through. For a homeowner racing a fast-moving notice period, a cash sale can close well before the auction date — preserving whatever equity is left instead of losing it at the courthouse steps. Call us today!
Alabama Foreclosure Data Summary
| Statistic | Figure | Source | Year |
|---|---|---|---|
| Alabama foreclosure starts, H1 2026 vs. H1 2025 | Up 26.6% (2,466 → 3,359) | ATTOM Mid-Year Report | 2026 |
| Alabama completed foreclosures (REOs), Q1 2026 vs. Q1 2025 | Up from 153 to 355 | ATTOM Q1 Report | 2026 |
| Alabama total filings, year-over-year | Up ~38.7% | ATTOM Q1 Report | 2026 |
| National mortgage delinquency rate | 4.37% | MBA National Delinquency Survey | Q2 2026 |
| National share of loans in foreclosure | 0.67% | MBA National Delinquency Survey | Q2 2026 |
| Alabama investor-owned home vacancy rate | 5.9% | ATTOM Vacant Property Report | Q3 2026 |
| Alabama statutory redemption period | 1 year after sale | Alabama Code / HB 90 | 2018–2026 |
Frequently Asked Questions
How fast can a foreclosure move in Alabama?
Once a lender starts the process, Alabama’s non-judicial system can move from notice to auction in a matter of weeks, since no court hearing is required.
Do Alabama homeowners get any time to reclaim their home after a foreclosure sale?
Yes — Alabama law provides a one-year statutory right of redemption, though it requires repaying the full sale price plus interest and costs.
Is Alabama’s foreclosure activity actually rising in 2026?
Yes. ATTOM’s data shows Alabama foreclosure starts up 26.6% and completed foreclosures more than doubling year-over-year in early 2026.
Methodology & Sources
Figures compiled by the Best Homes & Property Solutions team from ATTOM’s Q1 2026 and Mid-Year 2026 U.S. Foreclosure Market Reports, ATTOM’s Q3 2026 Vacant Property and Zombie Foreclosure Report, the Mortgage Bankers Association’s Q2 2026 National Delinquency Survey, and Alabama Code provisions on the statutory right of redemption (Ala. Code § 35-10-11 et seq.; § 6-5-248).
If you’re behind on your mortgage in Alabama and want to understand your options before a sale date is set, Best Homes & Property Solutions can review your situation and make a no-obligation cash offer. Contact us now!